01. Grant and pool calculations
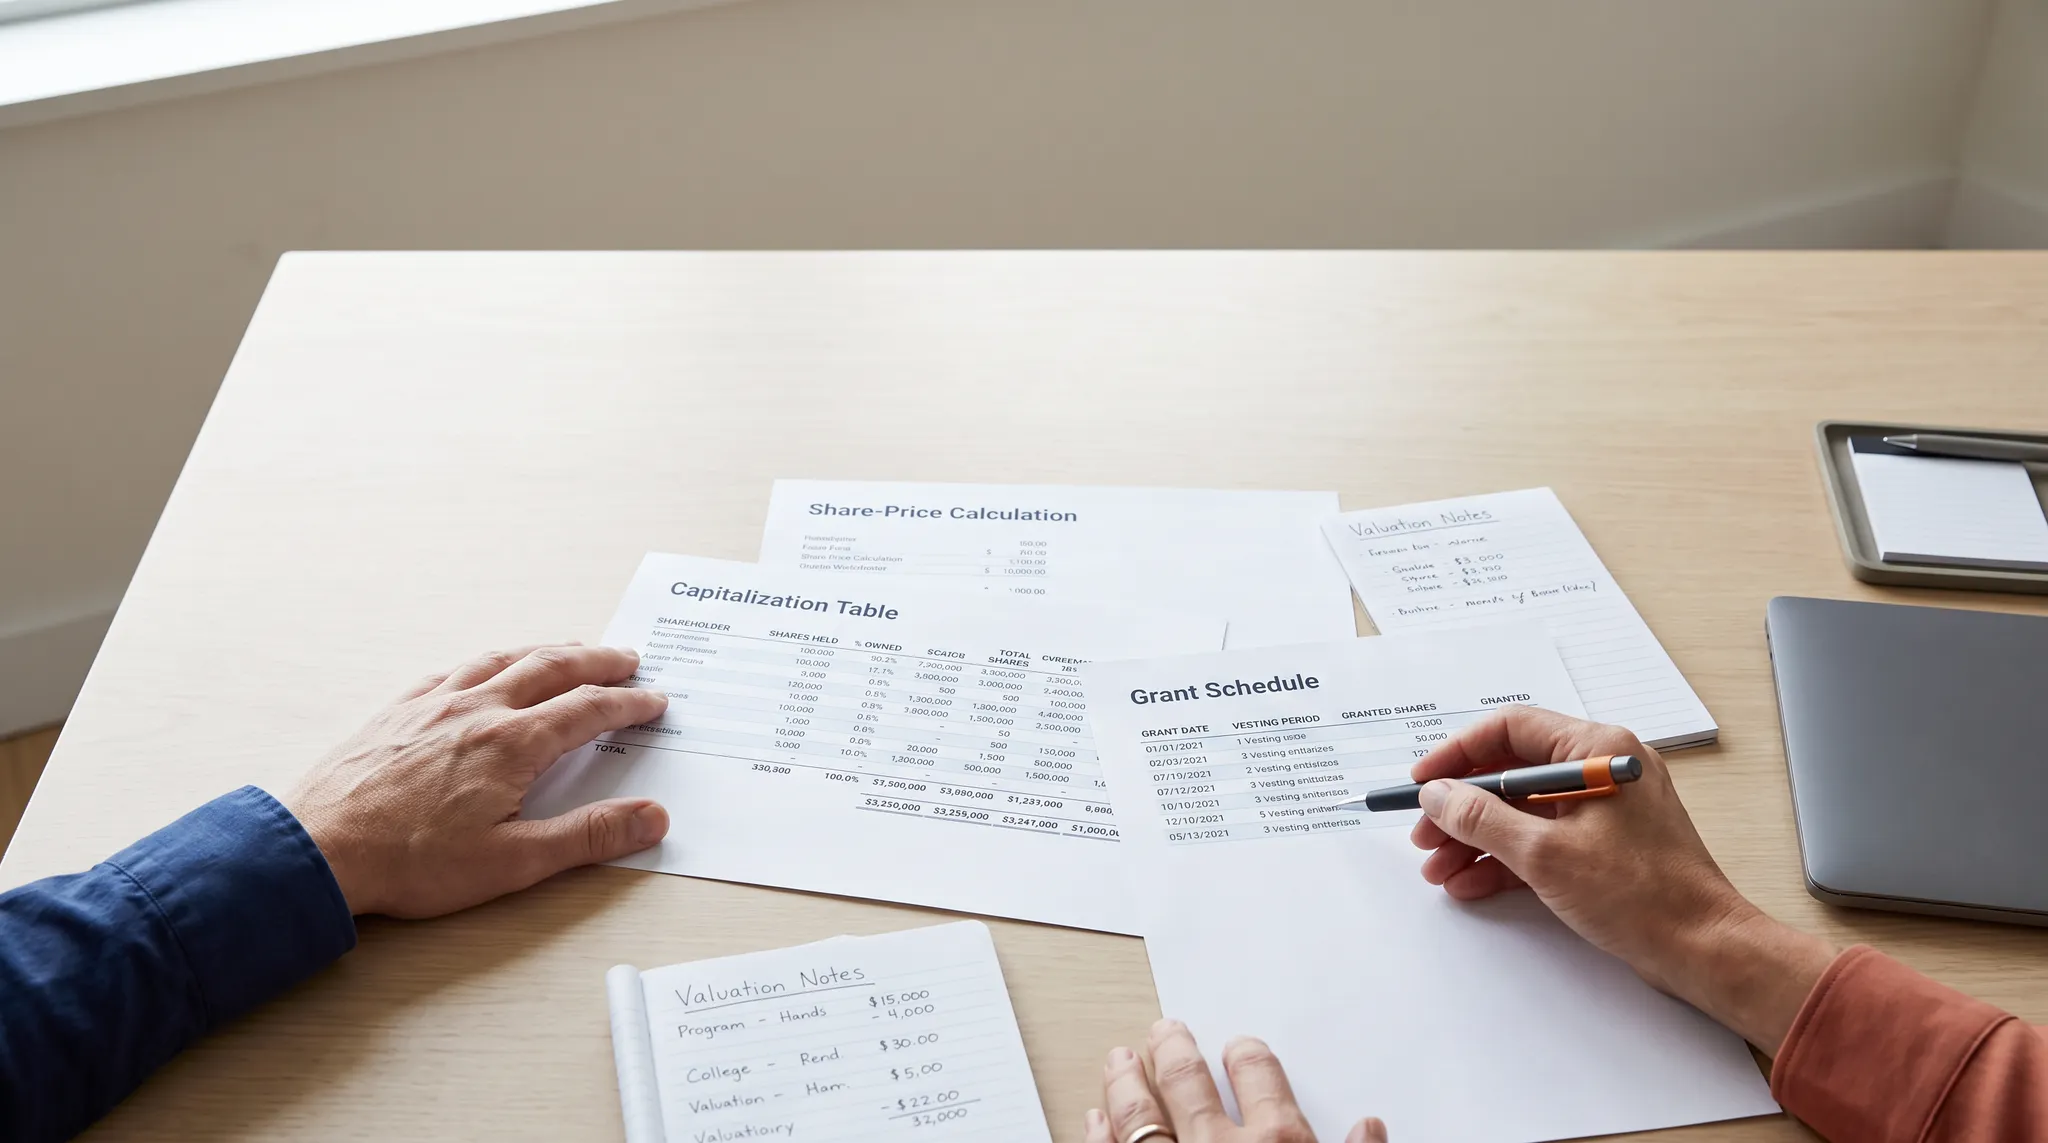
Calculate proposed grants as a share of the fully diluted capitalization, model option-pool changes and future dilution scenarios, and make the assumptions visible before a hiring decision.
Startup equity compensation
A grant affects ownership, exercise costs, and taxes. Work through the numbers before you issue options to your team.
Figures connects founder-level finance with in-house tax advice for U.S. employee stock options.
The consultation is free. We will agree on the scope and price before work begins.
The advisory work
Connect the option-pool calculation to valuation and tax questions before numbers go into an offer.
Calculate proposed grants as a share of the fully diluted capitalization, model option-pool changes and future dilution scenarios, and make the assumptions visible before a hiring decision.
Review the common-share fair market value used in grant and exercise scenarios. Figures helps examine the financial assumptions and coordinate with an independent specialist when a formal 409A appraisal is needed.
Estimate exercise cash, the share-value spread, and relevant timing for ISOs and NSOs.
Bring the cap table, grant terms, dates, and valuation assumptions together so founders and their legal advisers can make decisions using the same numbers.
Figures helps founders model proposed grants and option-pool effects, review exercise-price and fair-market-value assumptions, and work through U.S. tax timing for incentive stock options (ISOs) and nonqualified stock options (NSOs). The precise scope is agreed after we review your cap table, plan documents, and existing valuation.
No. A stock option plan sets the rules for grants. A 409A valuation is used to support the fair market value of private-company common stock for relevant tax purposes, including option pricing. Figures can review the financial assumptions and coordinate valuation questions; any formal independent appraisal and legal plan documents require the appropriate specialists.
For most NSOs without a readily determinable option value, the difference between the share value and the amount paid is generally included in income at exercise. ISO exercise generally does not create regular taxable income, but it may trigger alternative minimum tax. The later sale and ISO holding periods also matter. The right calculation depends on the grant, dates, values, and holder's circumstances.
An 83(b) election does not automatically apply to an ordinary stock-option grant. It may be relevant when substantially nonvested shares are actually transferred, including certain early-exercise situations. When available, the election generally must be filed within 30 days of the property transfer, not 30 days of a routine option grant.
Not in U.S. tax law. An employee stock ownership plan (ESOP) is a qualified retirement plan. Some startup guides use 'ESOP' informally for an employee option pool. This service addresses startup stock options and equity compensation, not the design or operation of a qualified retirement-plan ESOP.
Start with the equity plan and proposed grant terms, an up-to-date cap table, board approvals, and the common-share valuation used for the proposed exercise price. Legal counsel handles plan and grant documents. If employees exercise ISOs, the company also has IRS Form 3921 reporting obligations for the resulting share transfers.
We will confirm the scope and price after reviewing your stock-option needs. The $1,999 startup accounting and CFO plan covers the ongoing finance work described on its own page; it should not be read as a fixed-price quote for a separate equity-compensation project. Tax-return preparation and filing are scoped separately.
Tell us about your option pool, planned grants, and valuation or tax questions. We will discuss the right advisory scope and price in a free consultation.